Kikoff - Build Credit Quickly

Screenshots
Details
- Rating
- 16.04K reviews
- Version
- 1.170.2795
- Developer
- Kikoff Inc.
Analysis by Norviv
When I try a credit-building app, I pay as much attention to the steps that can slow someone down as to the headline promise. Kikoff is a finance app from Kikoff Inc., and its no-credit-check-needed approach may appeal if you are new to credit or wary of applying for another conventional product. But I would treat it as one possible part of a longer plan, not a quick fix: building a record takes time, and an app cannot make every outside factor affecting a credit profile disappear.
Where setup can feel less simple
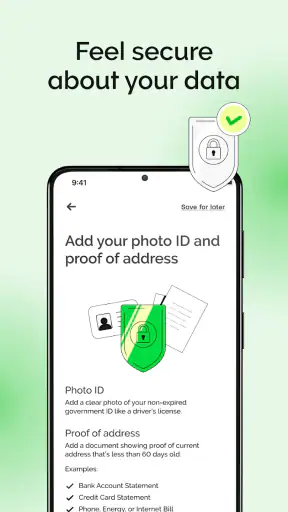
Signing up for a financial service can involve more than tapping through an introduction. Identity checks and account details are common points where a person may need to pause and make sure everything matches. I would enter information carefully, use details that are current, and read each screen before moving on rather than rushing through setup. That is especially sensible when the service is connected to your finances.
The “no credit checked needed” message may remove one worry, but it does not mean every part of enrollment is automatic or that approval and account access are guaranteed in every circumstance. If a step does not go through, I would first check the spelling and format of the information entered, confirm that the app is up to date, and try again when the connection is stable. Avoid repeatedly submitting the same details if the screen appears stuck; first give the process time to respond or use the app’s support route.
Checks worth making before you begin
Before starting, I’d decide what I want the service to help me do: establish a payment record, get a clearer understanding of credit, or build a routine around paying on time. That small decision makes it easier to judge whether the app’s approach fits. I’d also check that I can keep track of any recurring commitment involved and that I understand the terms shown in the app before agreeing to anything.
It is worth distinguishing a credit-building service from a general budgeting tool. Kikoff is designed around credit-building, so it is not a substitute for a full view of spending, bills, savings, and debt. If your main problem is losing track of household expenses, a budget app or a simple calendar reminder may solve that more directly. If you do proceed, keeping your own note of key dates and reviewing the account periodically gives you a backup beyond relying on any single notification.
When progress or access seems stalled
Credit information does not necessarily change the moment you make a payment or complete a setup step. If the app’s progress view seems unchanged, I would avoid assuming that something has failed immediately. Check whether there is an action waiting in the app, make sure any payment-related step is complete, and allow time for information to update. A tracker is useful for observing a trend, but it is not a live verdict on every financial decision.
If you cannot get past a screen, a practical recovery sequence is to close and reopen the app, check your connection, and confirm that you are using the current version. If the issue persists, contact support with a concise description of the screen and the step where it occurs. I would not send sensitive account information in an informal message or share verification codes with anyone who contacts me unexpectedly. Those habits are useful safeguards with any finance app, not a reason to assume something is wrong with Kikoff.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
When the cause may be outside the app
A credit score can reflect more than one service or payment pattern, so a flat result does not necessarily mean the app is malfunctioning. Other account activity, the timing of reporting, and information in a credit file can all affect what a person sees. If something looks inaccurate, I would compare the relevant account information and seek help through the appropriate financial or credit-reporting channel rather than expecting an app tracker to resolve every discrepancy.
I also would not judge success by a single score check. A steadier routine—knowing what is due, keeping commitments manageable, and reviewing changes over time—is a more useful measure of whether the approach is working for me. Kikoff can support that habit, but it cannot replace careful decisions about borrowing or guarantee a particular score outcome.
Getting Started with Kikoff
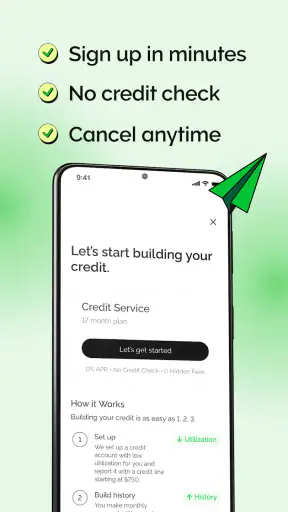
First things first, downloading Kikoff was a breeze. Available on both Android and iOS, the app is super lightweight and installed in no time. Registration was straightforward; I just needed to verify my identity and link a bank account. The interface is sleek and user-friendly, making the process less like a chore and more like a game.
Once logged in, you’re greeted with a dashboard that clearly outlines your credit-building journey. I particularly liked the step-by-step guidance on how to get started. From setting up a line of credit to tracking your progress, every feature is designed to be intuitive.
How Kikoff Works
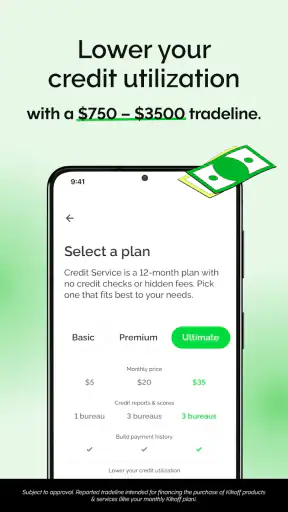
The app offers a $500 line of credit, which is essentially a credit builder loan. Unlike traditional loans, you don’t get the money upfront. Instead, you use it to pay for a subscription service provided by Kikoff. The idea is to show consistent, on-time payments, which helps boost your credit score.
One thing that stood out to me was the affordability. At just $2 per month, it's a small price to pay for potentially huge gains in credit score. Plus, there are no hidden fees or interest rates to worry about, which is a massive relief.
Features I Loved
Kikoff doesn’t just stop at providing a line of credit. It also offers educational resources that break down the often confusing world of credit building. The tips and tricks are practical, and I found myself learning a lot about financial management.
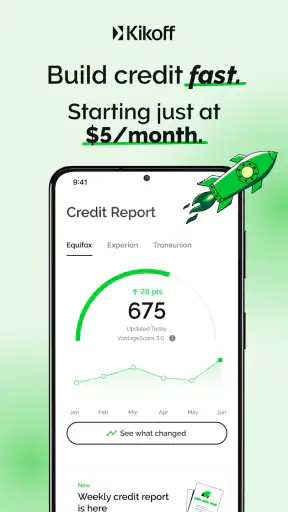
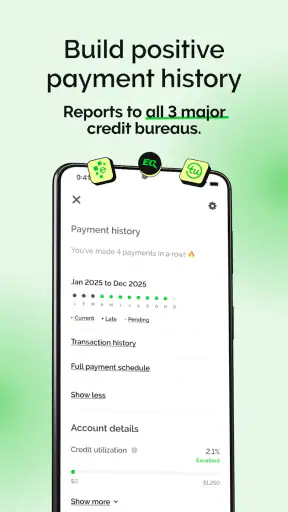
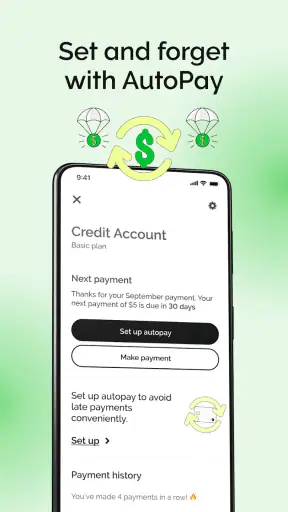
Another neat feature is the credit score tracker that updates monthly. It’s motivating to see the tangible impact of my efforts, and it helps keep me on track. I also appreciated the reminders for upcoming payments; life gets busy, and this little nudge is a lifesaver.
Community and Support
Feeling like you’re not alone in this journey is crucial, and Kikoff does a fantastic job of fostering a community vibe. The app has a built-in chat feature where you can connect with other users, share experiences, and even get advice. It’s like having a support group in your pocket.
If you ever run into issues, the customer support team is responsive and helpful. I had a minor hiccup during setup, and their quick resolution left me impressed.
Choosing it over familiar alternatives
People often compare credit-building apps with secured cards, credit-builder loans, or simply using a budgeting app and paying existing bills on time. Those options serve different needs. A secured card may be more useful if you want a card for purchases and can comfortably manage its balance. A traditional loan may suit someone who needs borrowed funds, while Kikoff’s described model is focused on building payment history rather than handing over cash to spend.
That distinction matters in everyday life. If your goal is to establish a manageable routine and you do not need a new spending card, Kikoff may feel more focused than a broad financial dashboard. If you already have a card or loan that you can handle responsibly, taking on another product may add complexity without being the right next step. I would compare the obligations and terms of any option, not just its potential credit benefit.
A routine that makes the app more useful
Imagine setting aside a few minutes on payday to open the app, check what is due, and make sure the money for scheduled commitments remains available. Then, later in the month, you can review the progress screen without expecting it to react instantly. That kind of simple routine is more valuable than checking a score every day; it turns the app into a prompt for consistency rather than a source of pressure.
A practical tip is to keep a separate reminder in your calendar for any important payment date, even if the app also provides reminders. This is not because I assume its alerts will fail; it is a low-effort backup when notifications are muted or a busy week throws off your routine. I would also avoid making a payment commitment based on a hoped-for score increase. Choose an amount and schedule you can maintain even if the score takes longer to change than expected.
Kikoff may be a particularly reasonable fit for someone starting with a thin credit history, who wants guided steps and is willing to check in consistently. It is less compelling for someone who wants immediate access to borrowed cash, needs a complete household budget, or is already struggling to cover existing obligations. In that last situation, adding another recurring commitment could create more stress than benefit; addressing essential bills and getting appropriate financial guidance should come first.
What to expect from the experience
The app’s strongest practical role is making a credit-building process feel visible and organized. Guidance, a progress view, and reminders can help turn an abstract goal into actions you can revisit. Still, a neat dashboard should not be mistaken for control over the entire credit system. I would use the score display as one reference point, alongside careful attention to account statements and any information available from relevant credit-reporting services.
It is also worth remembering that a good result is not guaranteed just because someone uses a credit-building product. Outcomes depend on a person’s broader circumstances and the information reflected in their credit file. I would approach Kikoff with patience, read the terms presented during enrollment, and reassess whether the ongoing commitment still makes sense for my budget. If it does not, the right response is to understand the account’s applicable options rather than simply ignore it.
Who should give it a closer look
Kikoff is free to download, is rated for Everyone, and has an average rating of 4.8 from around 122,000 ratings, with more than 5 million installs. Those figures suggest that many people have tried it, but popularity cannot tell me whether its particular approach suits my finances. I would use them as context, then focus on the terms, the steps required, and whether the app addresses my actual goal.
The app has been available since March 25, 2021, and its current version is 1.170.2795, with Android 7.0 as the minimum operating system. I would check compatibility before installing on an older device. Its free download is a low-friction way to explore the app, but the service itself should still be judged by the commitments and conditions shown during setup, not by the download price alone.
Final Thoughts
All in all, my experience with Kikoff has been overwhelmingly positive. It's a simple yet effective tool for anyone looking to build or improve their credit score. The combination of affordability, ease of use, and educational resources makes it a standout choice in the credit-building app market.
If you're just starting out on your financial journey or need a boost to your credit score, I’d definitely recommend giving Kikoff a try. It’s a small investment with the potential for big rewards.
So, are you ready to kick-start your credit journey with Kikoff? Trust me, your future self will thank you!
My practical verdict
I would recommend considering Kikoff if you want a guided, credit-focused routine and can keep any associated payment comfortably within your budget. I would skip it if you need cash in hand, want a general-purpose budgeting system, or would be better served by managing existing accounts before adding another commitment. For anyone who tries it, the useful approach is steady: understand the terms, keep track of due dates, and judge progress over time rather than expecting a fast change.
Frequently Asked Questions
01What is Kikoff and how does it work?
Kikoff is a financial app designed to help users build and improve their credit scores quickly and efficiently. By offering a $500 line of credit that reports to major credit bureaus, it helps users establish a positive credit history. The app focuses on responsible credit usage without the burden of high interest rates.
02Is Kikoff safe to use for building credit?
Yes, Kikoff is safe to use. It employs bank-level security measures to protect your personal and financial information. Additionally, it reports to major credit bureaus, ensuring your credit-building efforts are recognized. The app's straightforward approach helps users build credit without hidden fees or complicated terms.
03How much does Kikoff cost and are there any hidden fees?
Kikoff is notably affordable, with a monthly fee of just $2. There are no hidden fees or interest charges, making it a cost-effective option for those looking to improve their credit score. The app prides itself on transparency, ensuring that users are fully aware of any costs involved.
04Can Kikoff help me improve my credit score quickly?
Kikoff is designed to help users improve their credit scores efficiently by establishing a positive credit history. By responsibly using the $500 line of credit, users can see an impact on their scores as it reports to major credit bureaus. Consistent, responsible credit use can lead to noticeable improvements.
05What are the requirements to sign up for Kikoff?
To sign up for Kikoff, you must be at least 18 years old and a resident of the United States. The app requires basic personal information to verify your identity and set up your account. There is no credit check necessary to open the line of credit, making it accessible to those looking to build or rebuild credit.


